Detailed analysis of substantive topics
III.A and XI.A — Audit presentation and possible acceptance
Agenda p. 1 identifies Brad Porter of Lauterbach & Amen, LLP for a financial-audit presentation. XI.A, p. 2, separately allows review, discussion and a possible motion accepting statements for the fiscal year ending April 30, 2026. These are distinct agenda functions.
The October 5 communication letter on pp. 3–5 states that the governmental activities, major funds and aggregate remaining fund information were audited. It describes sensitive depreciation, pension and OPEB estimates; no significant difficulties or management disagreements; and says material misstatements detected were corrected. That wording must not be upgraded to a claim that there were no misstatements, no internal-control deficiencies, or an unmodified audit opinion. The letter expressly disclaims an opinion or assurance on required supplementary information.
Finance p. 39 says the full Audit Report will be available prior to the meeting. It is not included among these 103 pages; the August monthly schedules on pp. 50–70 are not the annual audited statements. No audit opinion can be confirmed from this packet alone. Decision point: whether to accept the separately supplied audited statements after presentation and review.
VI and VII.A–C — Agenda and consent record approvals
VI approves the current meeting agenda. VII groups approval of February 10 closed minutes, September 1 Committee of the Whole minutes, and September 8 Regular Board minutes. The February closed minutes are not publicly attached; that omission is not evidence of an unavailable confidential record. Approving closed minutes is not an authorization to release them. September minutes are historical context, not proof of October votes. Item references for the unavailable closed minutes use the agenda page only.
VIII.A — Expenditures and supporting schedules
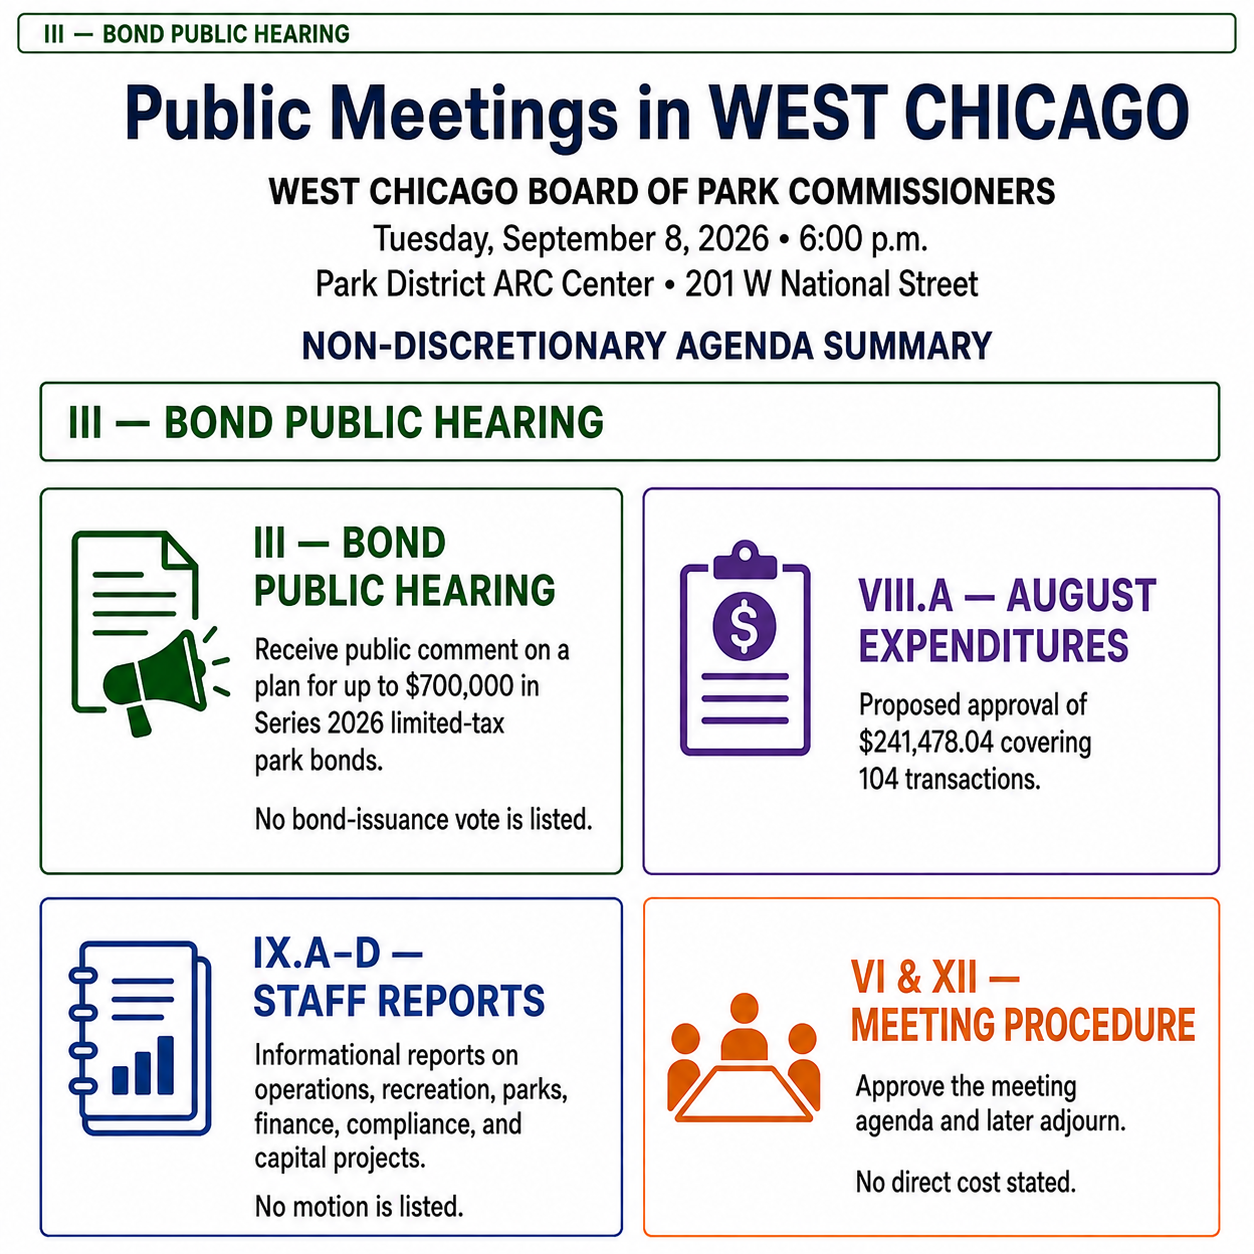
The September register ends on PDF p. 27 with a visually verified total of $635,950.84 and 180 transactions; both transaction amount and amount paid total that amount, with zero total balance. Examples on that page include Western DuPage Special Recreation Association $132,791.86 ($111,082.50 operating-dues installment and $21,709.36 inclusion), and Williams Associates Architects $1,726.02 for pool-filter bid assistance. These are already-incurred amounts in the register, not separate October contract approvals.
The separate monthly credit-card/utilities schedule p. 28 totals $39,365.62: ComEd $18,034.34, Nicor $5,489.72 and Visa $15,841.56. Payroll support gives September 4 total liability $73,572.73 and September 18 $62,990.97. Preserve those supporting figures without summing them into a fabricated combined approval total or implying they are incremental to the register. Decision point: routine approval of the named September report.
IX.A — Concrete future choices and current solar compliance
The Executive Director report pp. 33–34 describes work with District 94 on a shared recreational-facility intergovernmental agreement: school use of Pioneer Park and Kress Creek Farms Park, and Park District use of the school swimming pool. It explicitly says the agreement will come to the Board for approval once completed. No agreement, fees, term, or present approval motion is included. This is informational with a discretionary future decision and is flyer-eligible, with the future posture stated prominently.
The same report describes an additional solar panel/grid opportunity near Zone 250/old gun club: a 5MW system to store energy and generate projected income of about $62,000 per year. ComEd is reviewing the proposal; staff will meet again afterward to decide whether to bring it to the Board. This is a concrete informational opportunity with a discretionary future decision, not a recommendation to approve now, a guaranteed revenue stream, or a contract award. No vendor, installed cost, agreement or timeline is supplied.
The attached September 14 stormwater letter p. 35 concerns the existing Reed Keppler solar-panel site, not proof that the new Zone 250 concept is compliant. Following the September 11 inspection, it calls this the fifth notification of non-compliance, says native-vegetation mowing must cease, requests a written corrective response and annual monitoring reports due January 31, and plans reinspection in the 2027 growing season. It states the owner remains responsible until standards/sign-off; do not infer an assessed fine or assign contractual liability from this letter alone.
Health-premium sharing is under review, not an approved change: current medical 10% employee/90% District and dental/vision 3%/97%. No specific new contribution arrangement is recommended. An unincorporated-neighborhood park request north of Route 64/west of Route 59 is outside District boundaries and expressly not being actively pursued. A donated pergola opportunity did not work out. Those are not October approval proposals.
IX.B and IX.C — Recreation and Parks implementation
Recreation pp. 36–37 reports 1,171 memberships, Halloween preparations, District 33 curriculum-night childcare, rental revenue, annual risk review, and reduction of the winter guide from 28 to 20 pages for approximately $1,400 printing savings. The Kress Creek Farms soccer-field announcement received more than 22,000 video views and 2,200 reactions plus 30 new Facebook followers as of the report; those are outreach statistics, not an approval or construction schedule.
Parks p. 38 covers Pioneer playground replacement and fitness equipment intended for later 2026 if weather permits, otherwise early 2027; memorial-garden work; Turtle Splash offseason repairs; priority/hazard tree pruning to be bid for trees greater than 12 inches DBH, with smaller trees handled in-house; completed Cornerstone bridge planking following an engineer's stamped assessment; Hampton Hills and Turtle Pavilion paths; and continuing split-rail fence replacement. No new named contractor recommendation or amount is buried in this report. These are informational maintenance/implementation, not separate October purchase votes.
IX.D — Financial position, rating, benefits and HR
Finance/HR/Safety narrative pp. 39–41, S&P report pp. 42–46, PDRMA information pp. 47–49 and August all-funds schedules pp. 50–70 are preserved separately in the archive structure. Narrative surpluses of $448,925 Corporate and $233,598 Recreation describe four-month operating results, not cumulative reserves. The exact August schedule YTD operating surpluses are $448,925.85 Corporate (p. 51) and $233,598.24 Recreation (p. 56); distinguish these from staff’s whole-dollar presentation. Page 39 also says “first three months,” an internal period-description inconsistency; report the August 31 schedule date and do not silently rewrite the source.
The Executive Director p. 33 describes the new AA- rating with a positive outlook. Finance p. 39 and S&P's October 2 report instead give AA- with a stable outlook. Use the primary S&P stable outlook when describing the rating and flag the narrative conflict.
Finance p. 40 states PPO rate increase 15.9% and HMO 7.9%. The PDRMA board information p. 47 visually gives PPO 15.4%, HMO Illinois 7.9%, Blue Advantage HMO 8.7%, and HMO overall 8.6%. These are conflicting/scope-specific source statements; no single universal HMO increase should be inferred. Staff is studying 2027 benefits strategy, with no current agenda motion on the employer/employee split.
Paylocity contract extension and a two-year per-employee rate freeze are reported as earlier actions; a Recruiting module implementation call is scheduled October 15. No new extension motion or cost is listed. Staff reports 10 open part-time positions, 13 September new employees, training and a soccer-records FOIA request. The report's law discussion is informational, not an ordinance adoption by the Park District.
XI.B — Ordinance 26-03, Series 2026 limited bonds
The agenda identifies Ordinance 26-03; the draft on p. 72 leaves its ordinance-number field blank. The draft/forms pp. 71–100 are proposed material, including blank vote/certification fields. Printed “Adopted October 13, 2026” does not establish actual adoption in this pre-meeting packet.
The draft authorizes aggregate principal not exceeding $700,000, on taxable or tax-exempt basis, for refinancing a portion or all of December 1, 2026 principal/interest and June 1, 2027 interest on named Series 2017, 2023 and 2024A alternate-revenue obligations; broadly defined park land/facilities capital purposes; and issuance costs. The September 8 hearing is referenced as historical background, not a new October hearing. No itemized allocation between refinancing, projects and issuance expenses or particular capital-project commitment is provided.
Section 3 p. 75 sets a 6.00% interest ceiling and maturity no later than December 15, 2028, with principal due December 15 and interest June 15/December 15 as specified by Bond Order. Section 8 pp. 88–89 delegates sale/details to the Board President, Executive Director and Superintendent of Finance, without further Board authorization, with Stifel, Nicolaus & Company, Incorporated as placement agent selecting the purchaser. Purchase price is at least 98% of principal plus accrued interest. The subsequent Bond Order comes to the next meeting for information only, not an approve/reject vote. Final rate, purchaser, principal sold and payment schedule remain unset here.
Section 9, p. 90, specifies Pledged Taxes in each of the years commencing not before 2026 and ending not later than 2027, in a maximum amount of $705,000, with exact levy amounts set by Bond Order(s). This tax maximum is distinct from the $700,000 bond principal cap and is not an actual total levy, a calculated household increase, or an unconditional extension amount. Sections 9–13 provide a direct annual tax, bond/project funds and pledged use of proceeds. The annual tax extension for limited bonds is capped by the debt-service extension base, while the draft says no limit exists on the tax rate. Do not claim this creates an unlimited annual dollar extension or a calculated household tax increase. Decision point: authorize debt, tax pledge and delegated sale power; not merely pay an existing bill.
XI.C — Turtle Splash pool-filter renovation award
Agenda p. 2 proposes possible approval of the contract/award for $368,900.00 to “Stucky Construction Company.” Williams Architects' September 21 letter p. 101 repeatedly identifies “Stuckey Construction Company Inc.” The discrepancy must remain explicit; use attachment-qualified spelling rather than silently substituting it into the agenda.
The architect says apparent low bidder Crossroad Construction Inc. withdrew September 8, making Stuckey the second low bidder. Following a September 14 interview and internal reference checks, it finds no reason not to regard Stuckey as responsive/responsible and recommends award subject to evidence of all required insurance coverage. It reports confidence in the supplied timeframe but does not state that timeframe. The letter lists contractor interview and bid form/qualification attachments, but neither is separately included in this packet; no full bid tabulation or executed/draft contract is supplied. No contingency or budget cap separate from the $368,900 bid is provided.
Decision point: Board contract/vendor approval, not an already awarded contract. Despite the maintenance purpose, the actual procurement commitment is discretionary under the review rubric.
XI.D — Meadow Woods Park Section 4(f) concurrence
Wayne Township Road District's October 6 letter pp. 102–103 requests Park District concurrence in no adverse effects on recreational activities/features/attributes for a federally anticipated shared-use-path project, enabling FHWA's De Minimis finding process. The route runs from the West Branch DuPage River Trail to Army Trail Road via St Charles, Klein, Smith and Petersdorf roads, with an 8-foot shared-use path and a new pedestrian bridge south of the existing St Charles Road bridge.
A permanent easement from Meadow Woods Park would be needed along Klein Road's west side. However, the current signature text is a Section 4(f) concurrence, not an attached easement deed or blanket construction approval. No area, price, compensation, legal description or conveyance instrument is supplied. The letter says preliminary plans/exhibit are attached, but they are absent from this 103-page packet. It cites a September 8 public-information meeting and opportunity to comment; do not independently certify public-process adequacy from that statement alone.
Decision point: whether to concur with the no-adverse-effects/avoidance/mitigation findings and commitments based on the information available. This is a discretionary, property-specific authorization. It does not itself establish that FHWA has issued its finding or that a permanent easement has been granted.
XI.E — Soccer fields discussion
The agenda lists “Discussion- Soccer fields,” not a possible approval motion. Recreation identifies future soccer fields at Kress Creek Farms Park and the Executive Director describes a District 94 facility-sharing agreement involving that park. These support the location context but do not supply a design, bid, acreage, budget, schedule, or agreement for the fields. Decision point: discussion/planning direction only; do not imply the Board is awarding construction or adopting the shared-use agreement at this meeting.